Caribbean News
CIBC Caribbean announces a change to its Country Management Structure


New structure is expected to place renewed emphasis on employee,
community and client relationships as bank harnesses internal talent to lead new phase

Donna Wellington
Bridgetown, Barbados. 29th January 2025. The Caribbean’s leading financial services company, CIBC Caribbean, has announced a change to its Country Management, that will place greater emphasis on relationships with key stakeholder groups, including its employees, clients and the community. The bank currently operates in 10 Caribbean countries, having reduced its geographical footprint from 17 countries to 10 over the past three years.
In making the announcement today, Chief Executive Officer, Mark St. Hill, noted that leading the regional Country Management team, is the bank’s newly appointed Chief Country Management Officer, Ms. Donna Wellington, formerly Managing Director for Barbados & OECS, under whom all country-related activities will be aligned.
Donna Wellington is no stranger to Caribbean banking, having joined CIBC 20 years ago, holding progressively senior roles in the bank. She served as CIBC Caribbean’s Managing Director for the eastern Caribbean region since 2013, and between 2016 and 2021 was President of the Barbados Bankers Association, Director in the Barbados Private Sector Association (BPSA) and an active participant in the Barbados Social Partnership. In this regard she represents the BPSA as a participant in the Social Partnership Oversight Committee tasked with oversight of the Sustainable Recovery Plan for Barbados.
Mr. St. Hill noted: “Donna’s vast knowledge of banking and her commitment to client service makes her the perfect choice for this role. We know that she will bring the same energy to developing our business in the rest of the region that she brought to managing our operations in Barbados and the OECS.”

Kemar Polius
He added: “This change to the organization’s structure will mean that our other current Managing Directors with responsibility for the bank’s Operating Companies will transition to different types of roles in the organisation. CIBC Caribbean’s Managing Directors in The Cayman Islands and Jamaica, Mark McIntyre and Nigel Holness will be appointed the Chairmen of the Cayman and Jamaica businesses respectively, while taking early retirement from their day-to-day duties.
“Additionally, our MD in The Bahamas, Dr. Jacqui Bend, will take early retirement and transition to an assignment designed to assist us in our transformation and governance programme, while our MD in Trinidad, Anthony Seeraj, will remain with the bank until the end of fiscal. During this time his new remit will be to help us secure a new Head of Country for Trinidad, while assisting in a number of business development activities in Trinidad, after which he too will take retirement. We are also undertaking a search for a new Head of Country in The Bahamas to succeed Dr. Bend.”
Mr. St. Hill went on to add: “We feel extremely fortunate that these hugely experienced individuals will continue to be a part of our team, albeit in different capacities. We are also excited to announce a further evolution of our talent of professionals, to meet the demands of the new CIBC Caribbean, as we have appointed a new crop of Heads of Country to take over in five of our jurisdictions.
- Kemar Polius will succeed Ms. Wellington at the helm of the bank’s Barbados operations;

Gemel Sobers
- Gemel Sobers has been appointed the Head of Country for The Cayman Islands;
- Annique Dawkins is the Head of Country for Jamaica;

All Heads of Country will report to our newly appointed Chief Country Management Officer.” All appointments are subject to regulatory approval. St. Hill added: “We are shifting to a more country-focused performance model, having successfully optimized our geographical footprint from 17 countries to 10 and from 72 to 45 branches. This alignment emphasizes, at the country level, business development and performance, client facing activities and people leadership as we continue to embed our new corporate culture, which we started work on over the past year.”
He further explained that the new Heads of Country will prioritize the development of relationships, with staff, clients and within the community. “Our stated goal is to make our clients ambitions into reality. To do this, we must be closer to our clients, learning what they want from us and finding the best way to make it happen. A key component of that is ensuring our employees have the right tools, and the best working environment to deliver for our clients, so our Heads of Country will focus heavily on that, while ensuring we keep our commitment to contributing to the development of our communities.”

Annique Dawkins
The CIBC Caribbean CEO went on to list a number of major accomplishments of the regional bank over the past few years. “We have rationalized and consolidated our geographical footprint since 2016. We have enhanced our client experience and made several other structural adjustments such as integrating all our business segments under one Chief Commercial Officer, centralized key functions, launched an Agile way of working to give us a greater competitive edge, centralized our digital sales through our LoanStore, and revamped our Call Centers into Contact Centers. This is one more piece of the puzzle as we continue to develop our business capabilities and effectiveness.”
The new changes to the organization become effective on 1st March 2025.





By Deandrea Hamilton | Editor
September 28, 2026 – Wall Street initially flinched at the $3-billion handshake. But in a matter of days, it was smoother sailing.
Perhaps the bigger Caribbean business story is not what Sandals Resorts International is getting from the deal. It is who is writing the cheque — and what that says about what Gordon “Butch” Stewart built.
As reports of Royal Caribbean Group’s Sandals deal circulated Tuesday, RCL shares plunged 6.14 percent from Monday’s $250.25 close to $234.89, on sharply elevated trading.
When the agreement became official Wednesday — approximately $3 billion for a 50 percent equity interest in Sandals and Beaches Resorts — shares slipped another 1.95 percent to $230.30 and touched $222.22 intraday. Investors were digesting both the size of the investment and committed debt financing secured through Morgan Stanley.
But by Thursday, RCL rebounded 3.77 percent, with shares continuing their recovery Friday to finish the week around $243. Analysts were also looking ahead: JPMorgan reportedly raised its RCL price target from $345 to $394, while Citi placed the company on a 90-day positive catalyst watch.
And just who is RCL?
Royal Caribbean Group is a global vacation giant, publicly traded on the New York Stock Exchange with a market value of roughly $65 billion. Its portfolio includes Royal Caribbean International, Celebrity Cruises and Silversea, alongside private destinations and an expanding vacation platform.
So when a company of that scale commits $3 billion for only half of Sandals and Beaches Resorts, the transaction puts a striking financial marker on one of the Caribbean’s greatest home-grown hospitality success stories.
The deal, expected to close in early 2027, creates a 50-50 partnership with the Stewart family and takes Royal Caribbean deeper into the all-inclusive resort business.
Butch Stewart started Sandals in Jamaica in 1981 believing a Caribbean company could compete with the world’s best.
Forty-five years later, one of the world’s biggest vacation companies is prepared to pay $3 billion just to own half of what he built.
Now that’s the handshake that does more than seal a deal — it cements a legacy.
Caribbean News
Royal Caribbean Group and Sandals Resorts Announce Landmark Partnership to Accelerate Their Leading Vacation Experiences
Royal Caribbean Group Investment to Advance Sandals and Beaches’ Growth and Broaden the Group’s Vacation Portfolio
Montego Bay, Jamaica and Miami, September 24, 2026 – Royal Caribbean Group (NYSE: RCL) and Sandals Resorts today announced the signing of an agreement to form a partnership in the all-inclusive resort space with a 50% investment from Royal Caribbean Group. Building on Sandals and Beaches Resorts’ more than four decades of leadership in Caribbean hospitality, the joint venture will create new opportunities for continued resort growth while broadening the experiences across Royal Caribbean Group’s vacation platform.
The partnership brings together two of the travel industry’s most celebrated vacation companies, pairing Sandals and Beaches’ all-inclusive resort expertise with Royal Caribbean Group’s vacation platform, including industry-leading brands – Royal Caribbean, Celebrity Cruises and Silversea – a portfolio of private destinations, new river cruising offering, and an industry-first loyalty program. United in a shared history in the Caribbean and connected by a love for their communities, the companies will offer travelers an unparalleled collection of cruise, private destination and resort experiences, serving guests across more vacation occasions and establishing their undisputed leadership in Caribbean vacations.
The joint venture expands Royal Caribbean Group into an adjacent vacation category, growing its participation in the approximately $2 trillion global vacation market, and meets the growing global demand for Sandals and Beaches Resorts by accelerating their expansion. The partnership will include Sandals and Beaches’ collection of premier all-inclusive properties across the Caribbean, and the companies will explore opportunities to broaden distribution, deepen guest engagement, and make it easier for travelers to discover vacation experiences offered across both portfolios.
“For nearly 60 years, we’ve reimagined what a vacation can be, constantly expanding the ways we inspire our guests to explore, connect and create lifelong memories,” said Jason Liberty, Chairman and CEO, Royal Caribbean Group. “We have been building a vacation platform that brings joy to millions of people around the world and creates meaningful relationships that last with our guests. Our partnership with Sandals and Beaches Resorts is an important next step on that journey – bringing together two iconic leading vacation companies to further strengthen and grow one of the most admired resort portfolios in the world. The Stewart family has created powerful and beloved brands, and we are honored to build on that legacy. Together, we see tremendous opportunity to expand the reach of Sandals and Beaches Resorts and continue turning the vacation of a lifetime into a lifetime of vacations.”
“My father, Gordon ‘Butch’ Stewart, founded Sandals Resorts with the belief that a company built in the Caribbean could stand on the world stage alongside the most respected names in hospitality. Today is proof of how far that vision can go,” said Adam Stewart, Executive Chairman of Sandals Resorts and Beaches Resorts. “This partnership is the natural next step in building on that conviction. It gives us the ability to grow faster with a partner that shares our values of exceptional hospitality, long-term investment, and the power of enduring brands. Together, we will introduce more guests to Sandals and Beaches Resorts while creating even more extraordinary experiences for those who have made our resorts part of their lives for decades.” Stewart added, “As we continue to grow, we will remain true to what has always defined us: delivering authentic vacations that exceed expectations while creating opportunities for our team members, travel advisor partners and the communities we call home. The future has never been brighter, and I know this moment would make my father incredibly proud.”
The joint venture will be governed by a board under the shared leadership of Stewart and Liberty. Stewart will maintain a leadership role in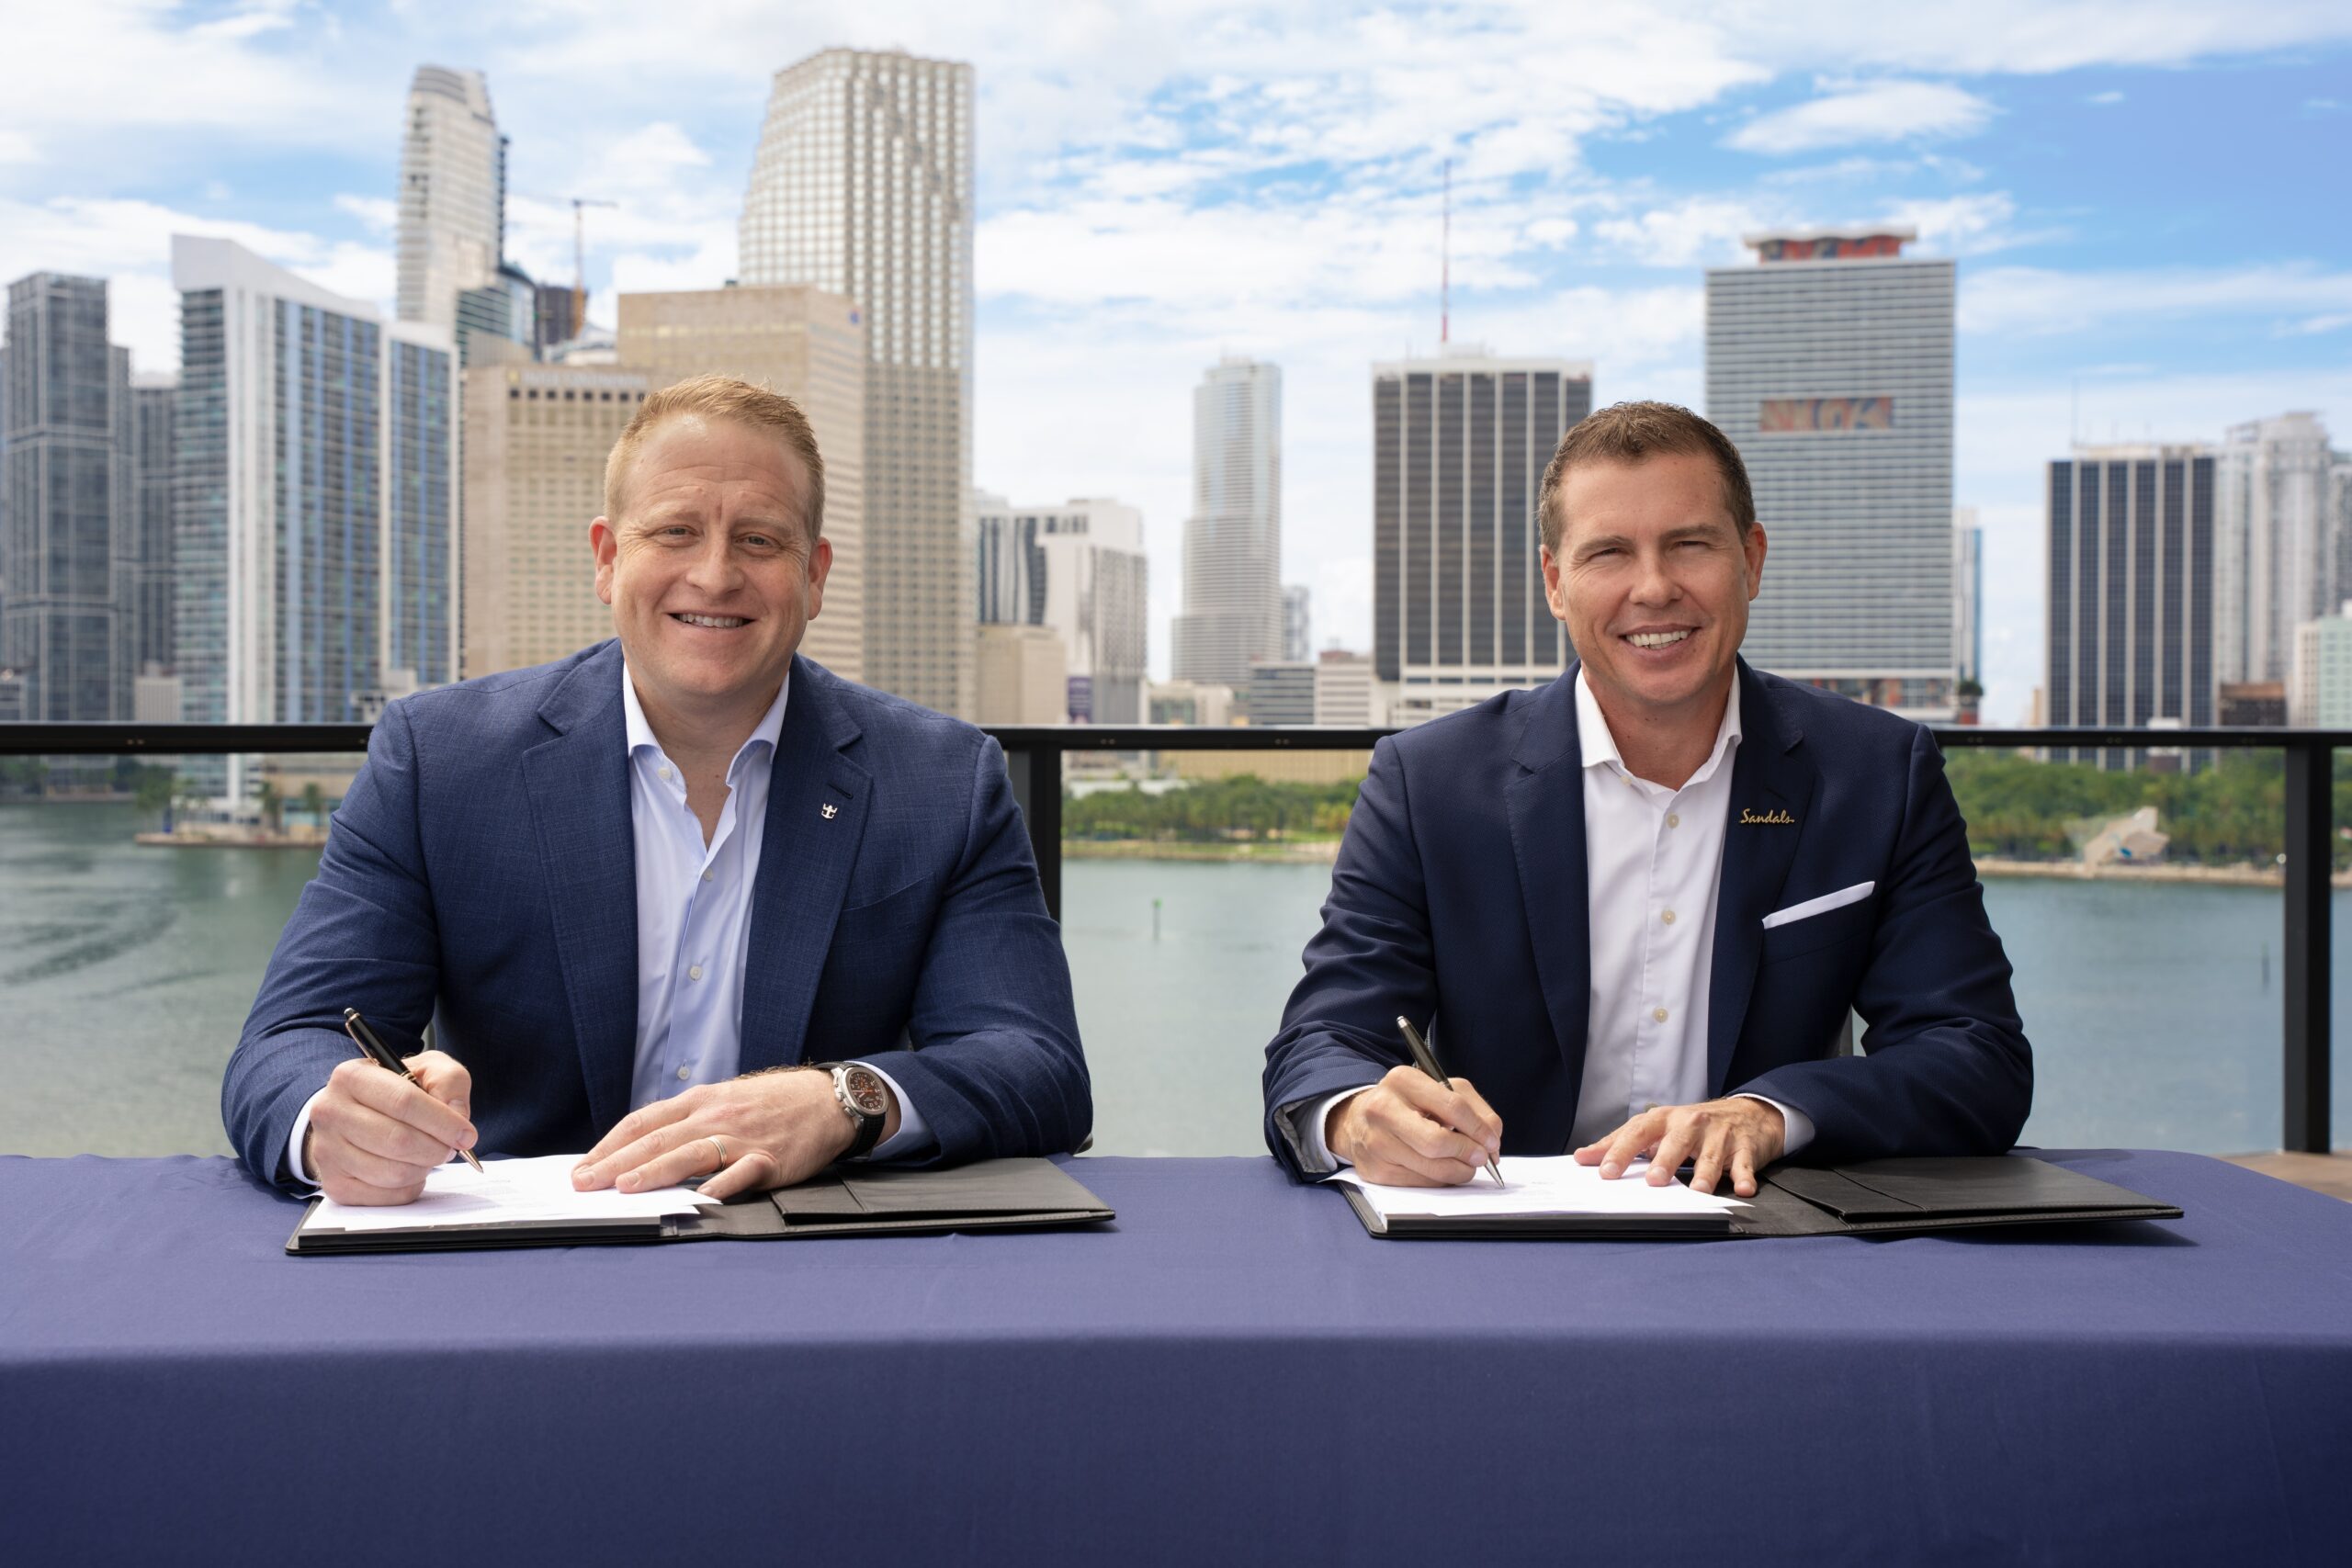 guiding the company’s long-term strategic growth as Executive Chairman of Sandals and Beaches Resorts. Existing reservations, loyalty programs, resort operations and cruise operations will continue as usual, with the partnership bringing additional resources to support future opportunities.
Under the terms of the agreement, Royal Caribbean Group will acquire a 50% equity interest in Sandals and Beaches Resorts for approximately $3 billion, representing a forward EBITDA multiple of approximately 10x. Royal Caribbean Group has secured committed debt financing from Morgan Stanley to fund the investment. The transaction is expected to close in early 2027, subject to customary approvals and closing conditions, and is expected to be accretive to earnings next year.
BofA Securities and PJT Partners acted as financial advisors, and Latham & Watkins and Jones Day acted as legal advisors to the Sandals Group. Perella Weinberg Partners and Morgan Stanley acted as financial advisors and Kirkland & Ellis LLP acted as legal advisor to Royal Caribbean Group.
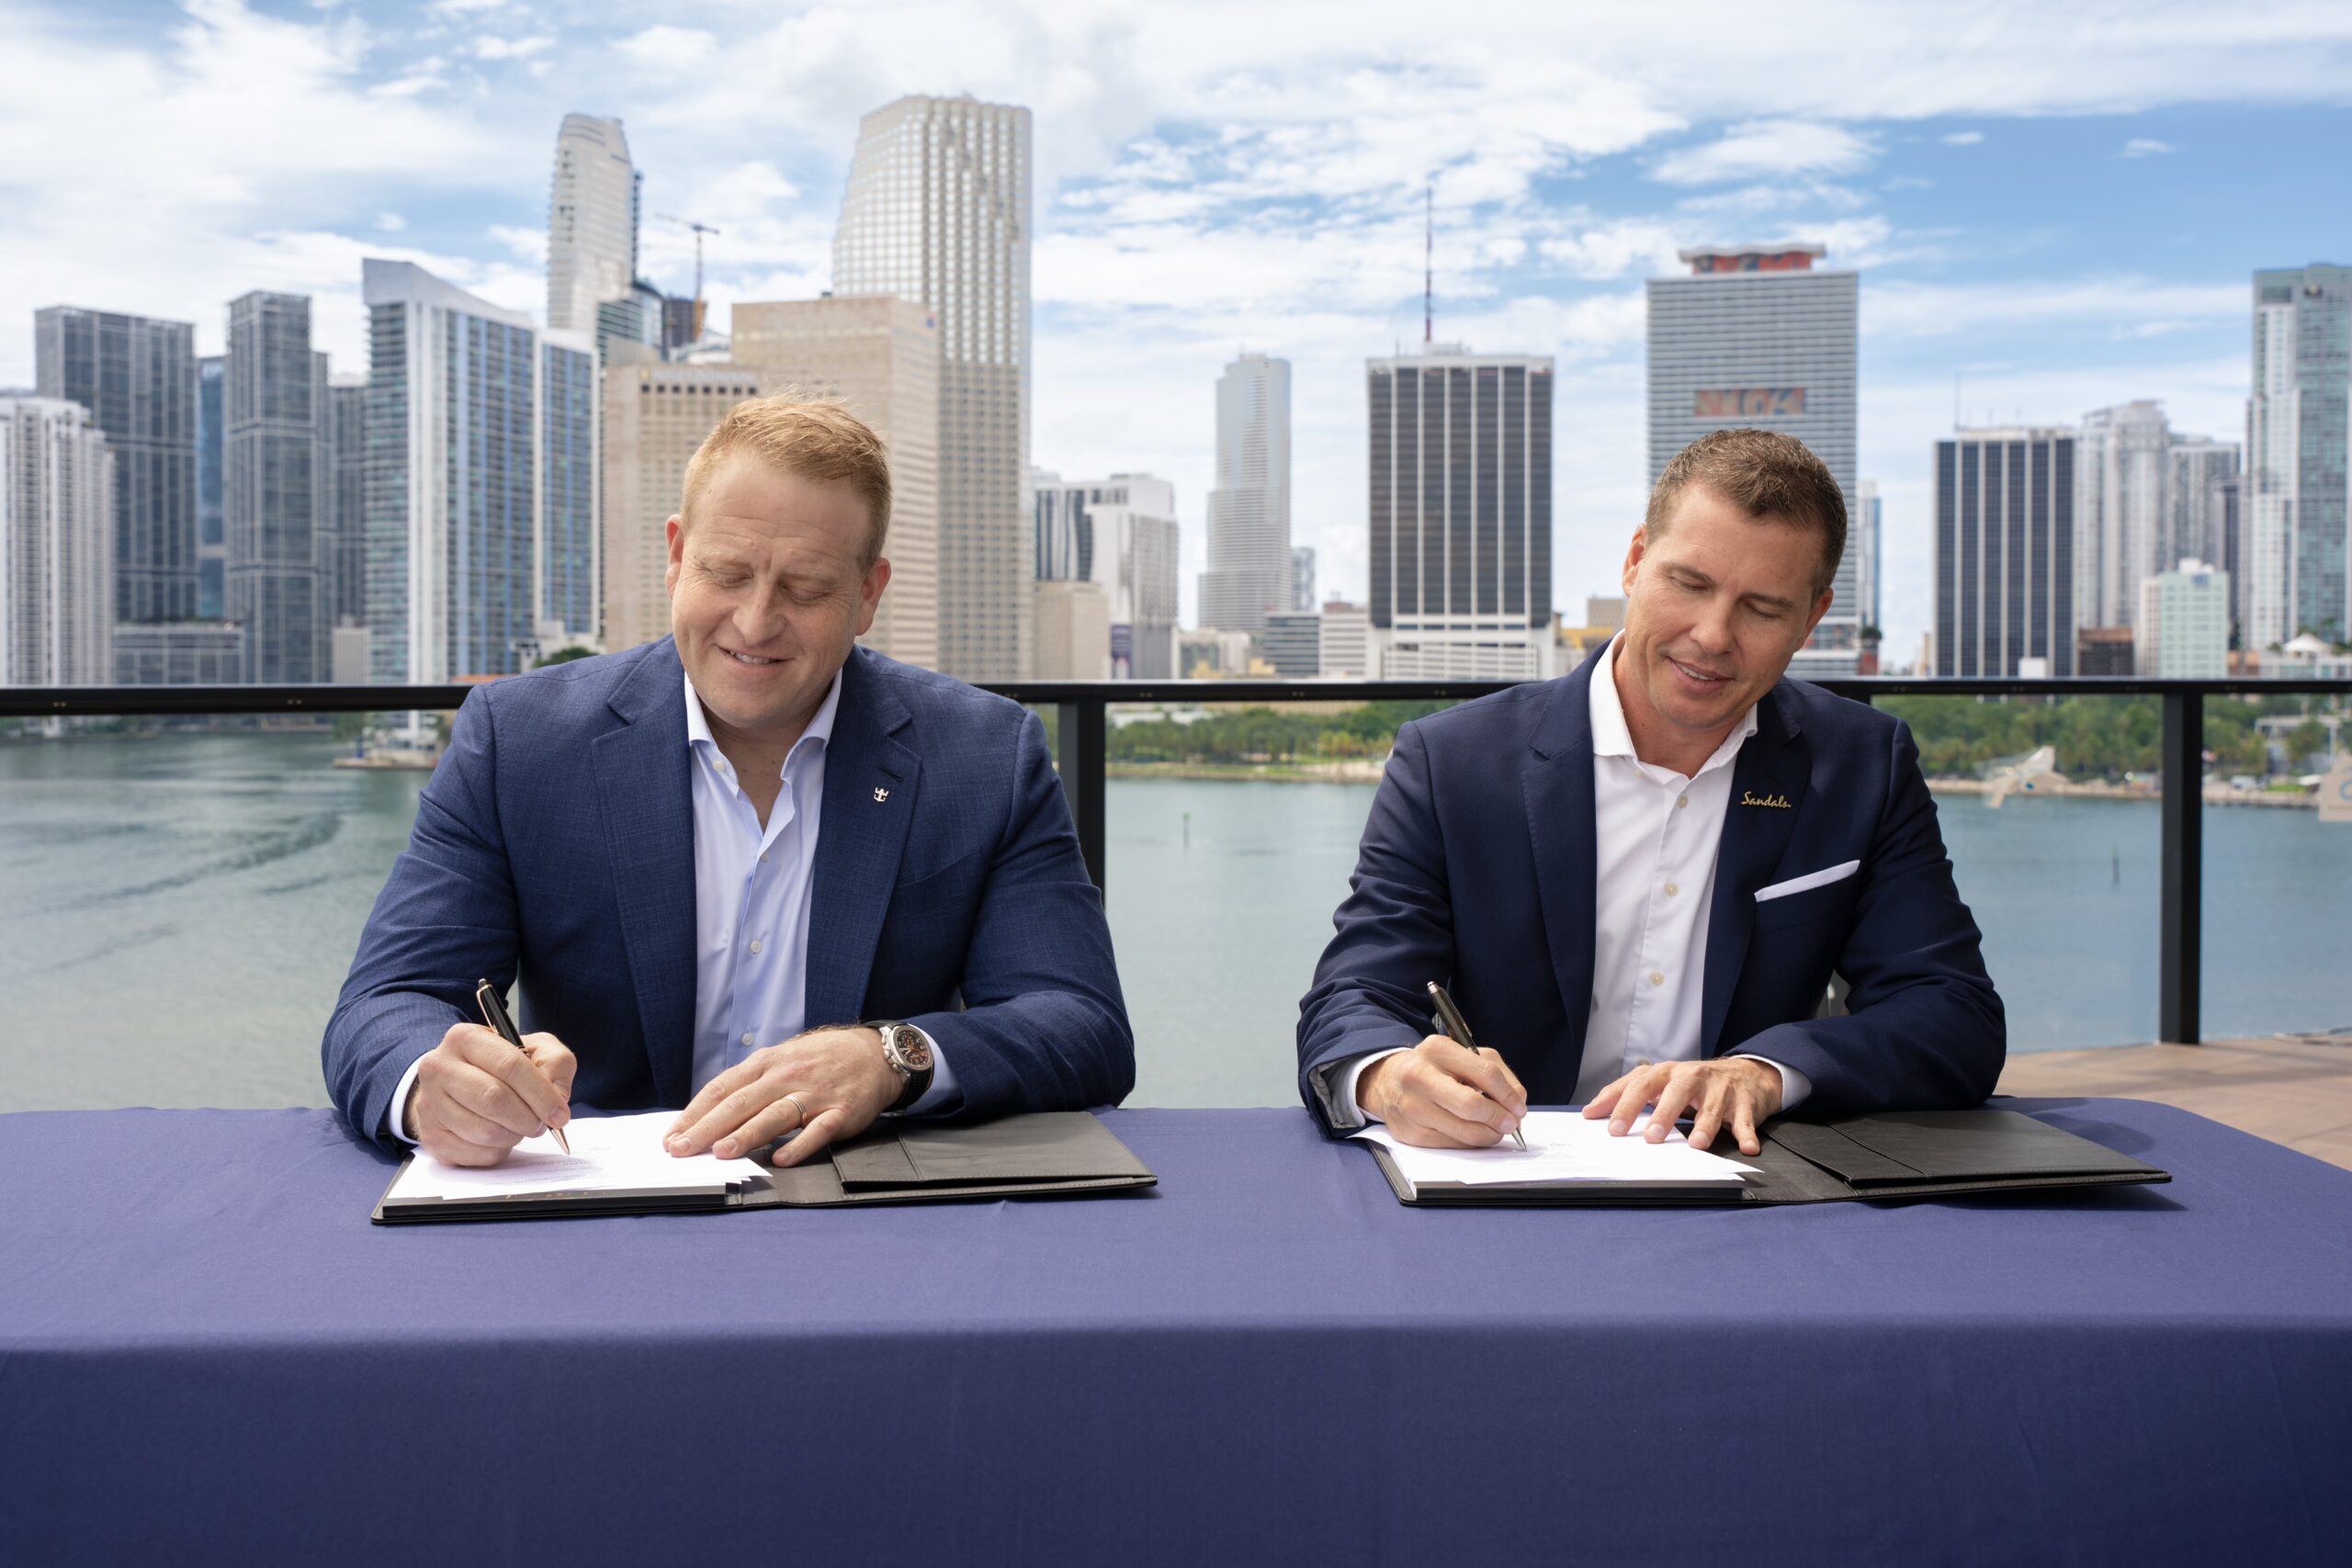
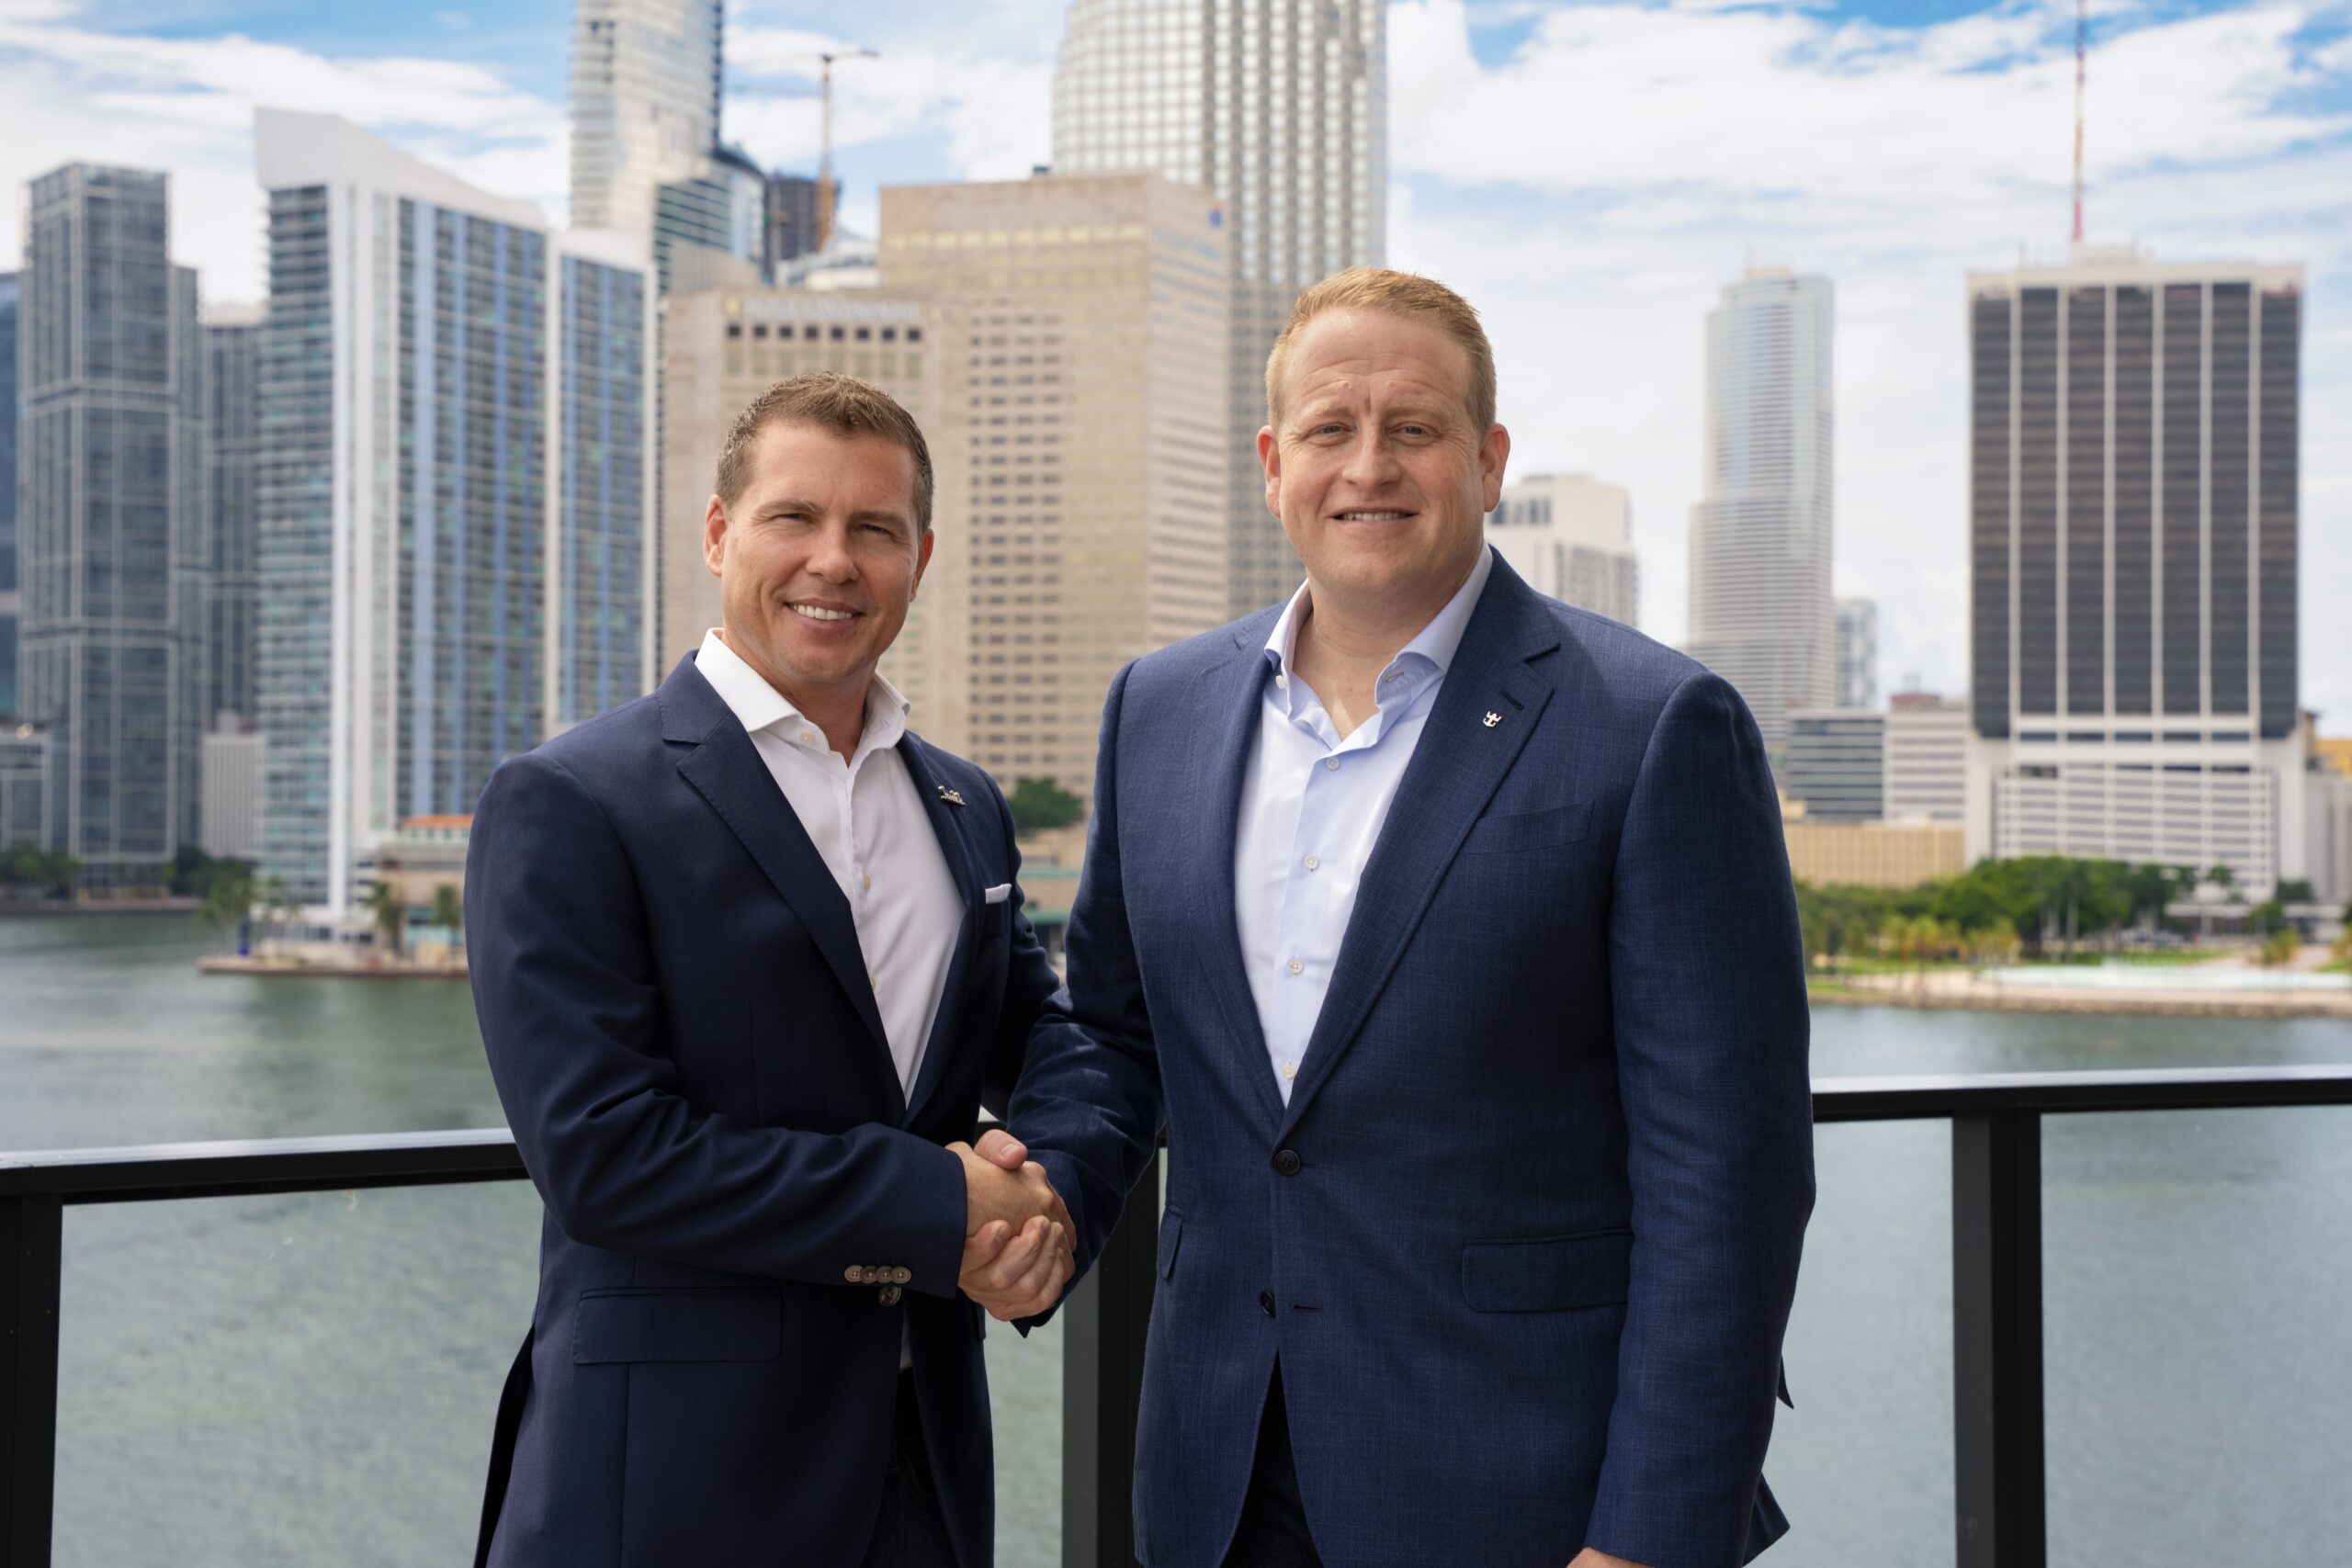
PHOTO CAPTION: Jason Liberty, Chairman and CEO of Royal Caribbean Group, and Adam Stewart, Executive Chairman of Sandals Resorts, mark the signing of an agreement to form a landmark partnership that expands Royal Caribbean Group into the all-inclusive resort space and supports the future growth of Sandals and Beaches Resorts. The signing took place at Royal Caribbean Group’s new headquarters in Miami, with the city’s skyline in the background.
The Caribbean tourism deal first reported as a possibility on Tuesday is now a signed agreement. Royal Caribbean Group plans to pay approximately US$3 billion for a 50% stake in Sandals and Beaches Resorts, putting the value of the business at about US$6 billion. The purchase is expected to close in early 2027, subject to approvals.
Founded in Jamaica by the late Gordon “Butch” Stewart in 1981, the resort business has a presence across nine Caribbean destinations, including Jamaica, The Bahamas and Turks and Caicos. Sandals has described its workforce as nearly 20,000 people, most of them Caribbean nationals.
“My father, Gordon ‘Butch’ Stewart, founded Sandals Resorts with the belief that a company built in the Caribbean could stand on the world stage alongside the most respected names in hospitality,” said Adam Stewart in the announcement carried by PR Newswire. He will remain executive chairman, while the Stewart family retains a stake. The companies say existing reservations and resort operations will continue as usual.
-
 Bahamas News1 week ago
The Bahamas Reaffirms Support for Ukraine at International Conference in Toronto
-
 Bahamas News1 week ago
Walk for the Cure Every Saturday This October
-
 News1 week ago
Invest Turks and Caicos Officially Opened Caya Hico Collective, Grand Turk MSME Storefront
-
 Health1 week ago
TCI Hospital Marks Breast Cancer Awareness Month 2026 with “Know. Check. Act. Support.” Campaign
-
 Health5 days ago
Cleveland Clinic First in Ohio to Perform Robotic Nipple-Sparing Mastectomy